Is Flexxbuy Worth It?
★★★★★ 3.5/5
Quick Verdict: Flexxbuy is a solid pick if you sell high-ticket services and lose deals over price. One application reaches 30+ lenders, so more of your customers get approved. The catch? It’s a lender marketplace, not a full checkout system, and rates depend on each lender.
✅ Best For:
Service businesses, clinics, coaches, and home improvement pros who sell $1,000+ jobs
❌ Skip If:
You sell low-cost items online and just need a “pay in 4” button at checkout
| 📊 Lender Network | 30+ lenders | 🎯 Best For | High-ticket services |
| 💰 Price | From $149 (Pro Plan) | ✅ Top Feature | One multi lender application |
| 🎁 Free Trial | No | ⚠️ Limitation | Rates set by each lender |
How I Tested Flexxbuy
🧪 TESTING METHODOLOGY
- ✓ Broke down both pricing plans line by line
- ✓ Read through 249 merchant reviews on Trustpilot
- ✓ Studied the merchant dashboard and application flow demos
- ✓ Checked lender loan ranges, terms, and starting rates
- ✓ Compared it against 5 popular alternatives
Ever watched a customer walk away over price?
They love your service. They just can’t pay a few thousand dollars today.
Their bank says no. Or the card has high interest they won’t touch.
Enter Flexxbuy.
It lets your customers split the cost into affordable monthly payments.
In this Flexxbuy review, I’ll show you what works, what doesn’t, and who should pay for it.
Flexxbuy
Stop losing deals over price. Flexxbuy sends one application to 30+ lenders, so more of your customers get approved. Merchants often get paid within 24 to 72 hours.
What is Flexxbuy?
Flexxbuy is a customer financing platform for small and growing businesses.
Think of it like a loan broker that lives inside a link.
Here’s the simple version.
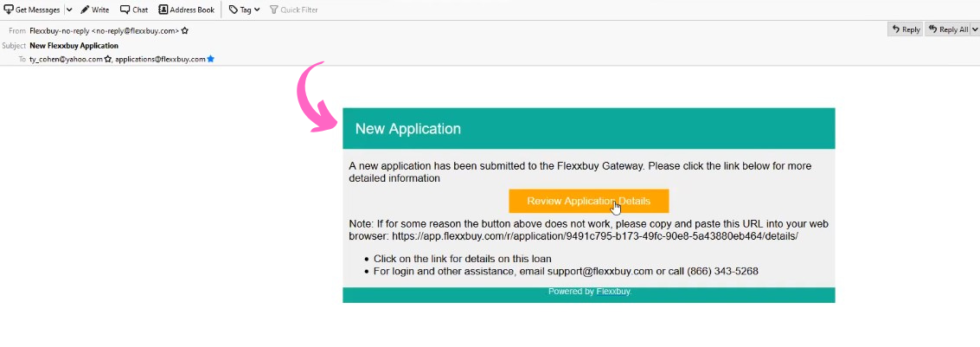
You send your customer one simple application.
That form goes out to multiple lenders at once.
Your customer reviews the offers and picks the payment path that fits.
Customers receive real financing options, not one take-it-or-leave-it offer.
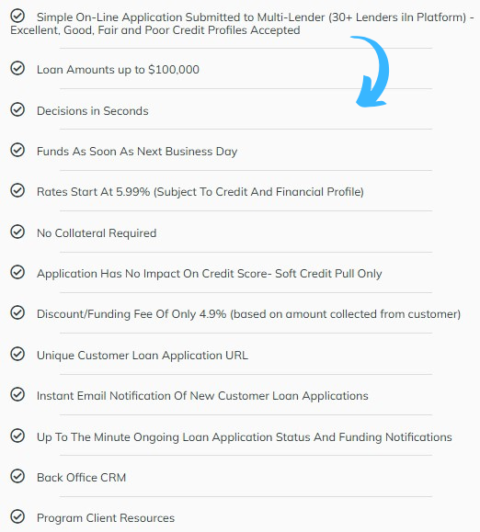
Loan amounts typically range from $500 to $100,000.
Some lender programs start at $1,000, depending on the program and your business.
Once approved, the funds go to the customer or to your business directly.
The tool focuses on approval odds, not just checkout buttons.
Unlike standard BNPL (buy now, pay later) apps, Flexxbuy covers a broader range of credit profiles.
That includes near prime and sub-prime buyers that most checkout apps turn away.
It also works in places BNPL often skips, like elective healthcare, legal services, and home improvement.
Who Created Flexxbuy?
Bob Lovinger leads Flexxbuy as its president.
The idea is simple. Small businesses should get the same financing power that big industry leaders enjoy.
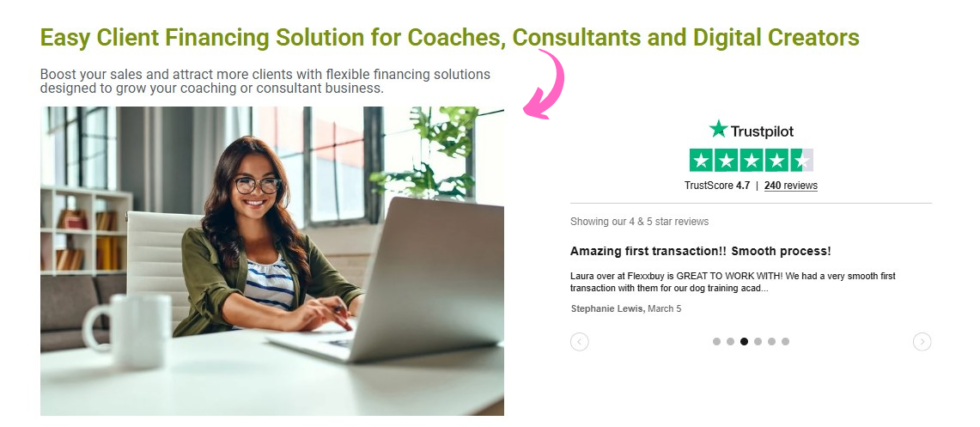
Banks rarely help a dog training academy or a solo life coach offer financing.
Flexxbuy fills that gap without bank underwriting headaches.
The mission is empowering businesses of all sizes, from startups to established shops.
Through one link, small businesses access financing solutions once reserved for big brands.
Today, Flexxbuy has:
- A network of over 30 lenders
- A 4.8/5 TrustScore from 249 Trustpilot reviews
- Merchants across retail, healthcare, education, and home services
The company is based in Port Saint Lucie, Florida.
Top Benefits of Flexxbuy
Here’s what you actually get when you start offering financing with Flexxbuy:
- Close More Sales: Customers stop staring at the total price. They focus on a monthly number they can handle.
- Higher Approval Rates: One application hits 30+ lenders. Better credit and weaker credit both get a fair shot.
- Bigger Tickets: Financing boosts your customers’ buying power. They say yes to the premium package, not the cheap one.
- Faster Cash Flow: Merchants often receive funding within 24 to 72 hours. No waiting on slow bank models.
- More Deals Stay Alive: When price is the problem, you have a second path to close. That alone can increase sales.
- Wider Market Reach: You can serve near prime and sub-prime buyers your competitors turn away. It works across most industries.
- Cost Efficiency: A flat plan fee replaces building your own lender relationships. You keep more revenue.
Best Features of Flexxbuy
Here are the five tools that make Flexxbuy a real financing platform.
1. Client Financing Solution
This is the core of Flexxbuy.
You get a personalized page with your own application link.
Send it by text, email, or show it in person.
The application process takes under a minute if your customer knows their income and social security number.
From there, the whole process stays digital, from application to funding in a few days.
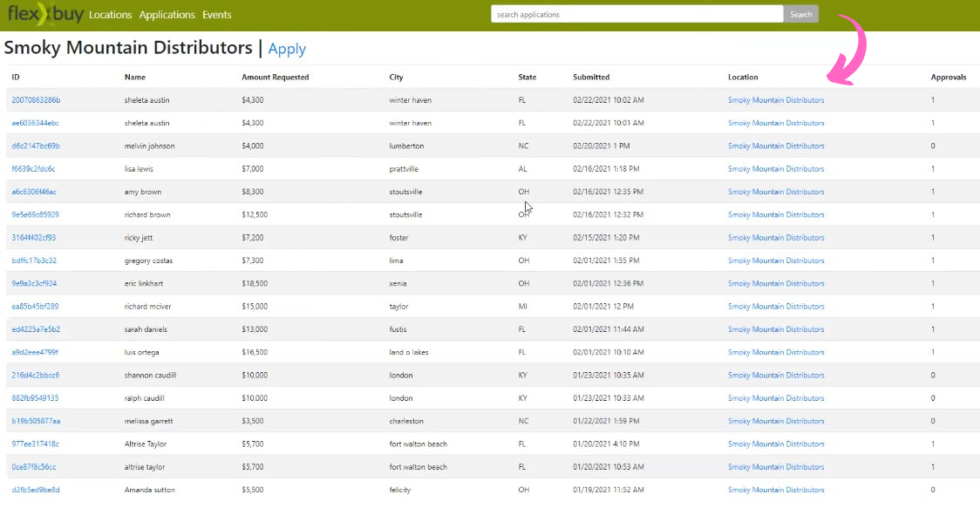
2. Applications Manager
Every application lands in one dashboard.
You see who applied, who got approved, and who’s still waiting.
That makes follow-up easy.
Your team can assist clients the moment an approval comes in.
If a customer stalls, you know exactly when to call and push the closing process forward.
Reviewers often call the dashboard extremely user friendly, even for owners who hate software.
3. Lending Partners
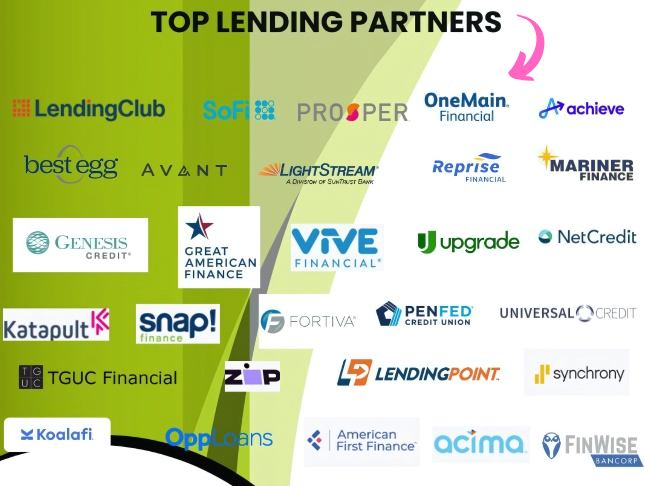
This is where Flexxbuy beats single-lender apps.
Flexxbuy partners with over 30 lenders.
A credit select step matches each applicant to lenders that fit their profile.
Many lenders run a soft credit pull first, so checking offers won’t hurt credit scores.
Instant decisions come back from several lenders at once.
More lenders means more options and more approvals.
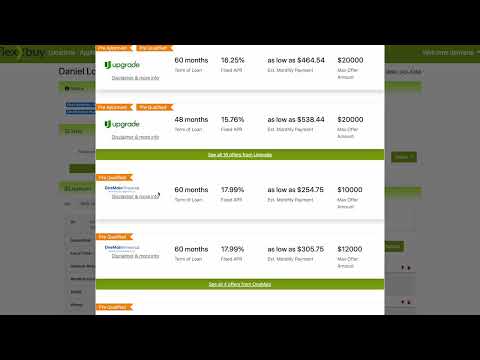
4. Detailed Payment Grid
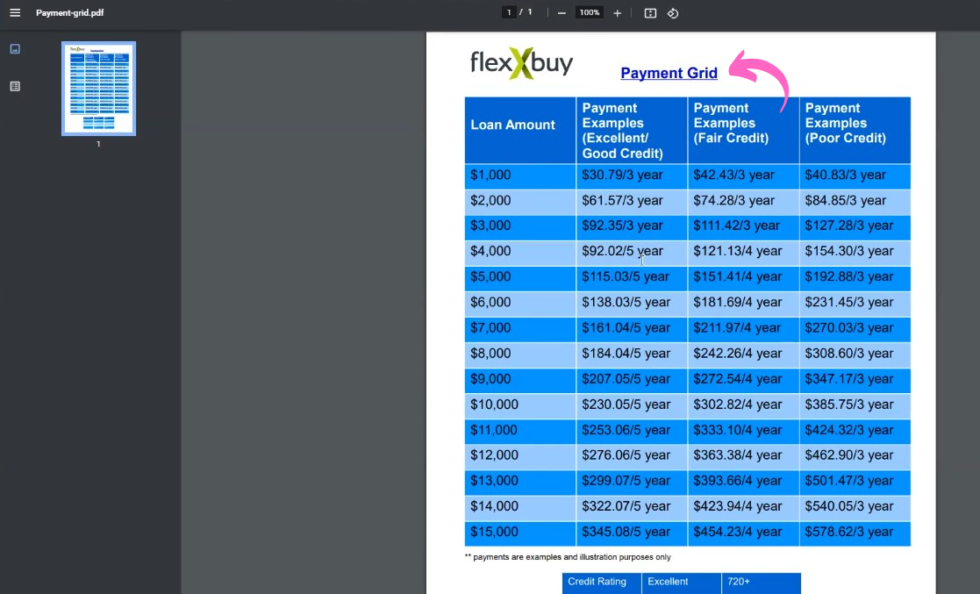
The payment grid shows every offer side by side.
Your customer sees the monthly payment, term, and rate for each one.
Loan terms usually run from 24 to 84 months, and many programs cap at 72.
Rates can start as low as 4.9% for strong credit.
This gives customers flexibility and confidence before they sign anything.
5. Reports Analyzer
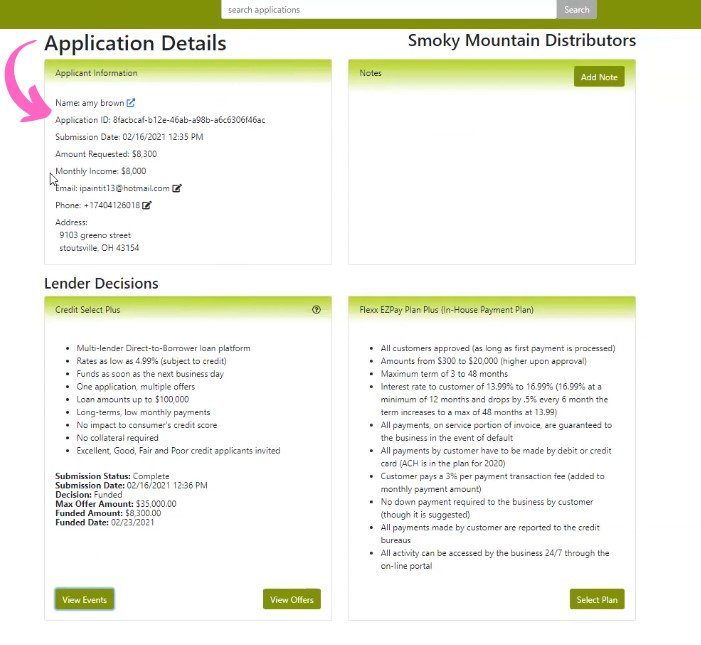
Reports show how financing affects your numbers.
You can track approval rates, funded amounts, and which lenders say yes most.
That tells you if offering financing actually brings in more sales.
It also shows how much extra cash hits your account each month.
Flexxbuy Pricing
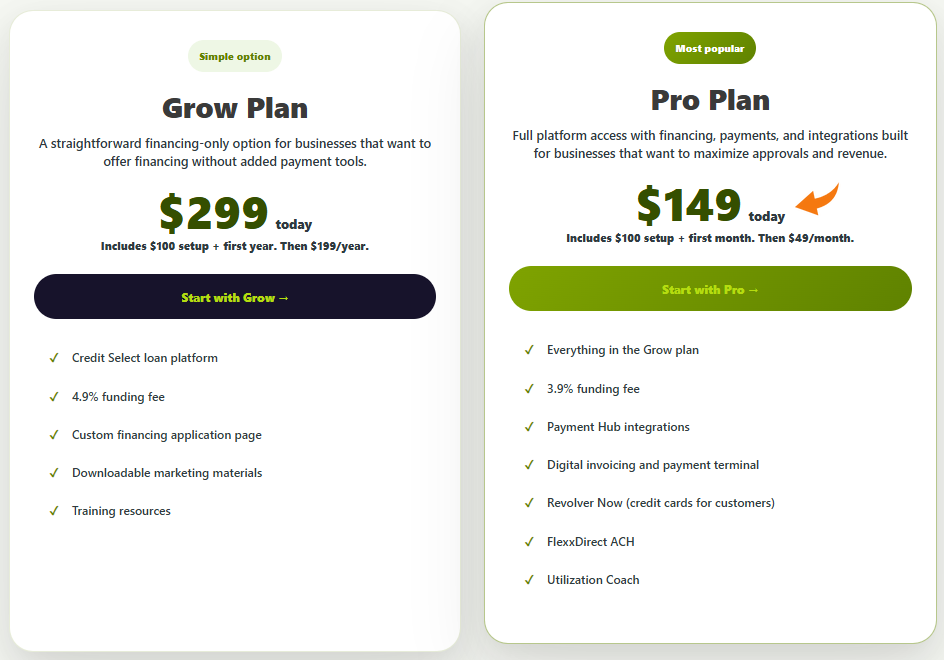
Flexxbuy has two plans. Both include a $100 setup fee.
| Plan | Price | Best For |
|---|---|---|
| Grow Plan | $299 (Includes $100 setup + first year. Then $199/year) | Businesses that want one yearly bill and the lowest long-term cost |
| Pro Plan | $149 (Includes $100 setup + first month. Then $49/month) | New users who want to test financing with less money upfront |
Free trial: No. You pay the setup fee to start.
Money-back guarantee: Not listed publicly. Ask the sales team before you pay.
📌 Note: The Grow Plan costs $199/year after year one. The Pro Plan costs $588/year at $49/month. Yearly saves you $389.
Is Flexxbuy Worth the Price?
For most service businesses, yes.
One extra $3,000 sale pays for years of the Grow Plan.
The real cost to watch is lender fees, which vary by program.
You’ll save money if: You close even one financed deal per month that you’d otherwise lose.
You might overpay if: Your average sale is only a few hundred dollars.
💡 Pro Tip: Start on the Pro Plan for two or three months. If financed deals come in, switch to Grow and cut your yearly cost.
Flexxbuy Pros and Cons
✅ What I Liked
30+ lenders in one app: One form reaches many lenders, which raises approval odds.
Works for most credit types: Prime, near prime, and sub-prime buyers can all find offers.
Soft pull first: Many lenders check credit without hurting the customer’s score.
Fast merchant funding: Payouts often land within 24 to 72 hours.
Low, flat plan cost: Plans start at $149, with no per-seat pricing.
❌ What Could Be Better
No free trial: You pay a $100 setup fee before you see a single approval.
Rates vary by lender: Sub-prime customers may see high interest offers.
Not a checkout button: It’s built for quotes and invoices, not quick online carts.
🎯 Quick Win: Mention financing early in your sales call, not at the end. It changes the money talk from “too expensive” to “what fits your budget.”
Is Flexxbuy Right for You?
✅ Flexxbuy is PERFECT for you if:
- You sell services worth $1,000 or more, like home improvement or legal work
- You need patient financing for dental, cosmetic, or other elective care
- You’re a coach or school that wants coach financing for your program
- You want easy customer financing without bank paperwork
❌ Skip Flexxbuy if:
- You need a “pay in 4” button on a Shopify store
- Your average sale is under $500
- You want one lender with one fixed rate for every customer
My recommendation:
If price objections kill your deals, get Flexxbuy.
It gives your sales team real closing power.
If you sell cheap products online, pick a BNPL app instead.
Flexxbuy vs Alternatives
How does Flexxbuy stack up against other consumer financing tools? Here’s the landscape:
| Tool | Best For | Price | Rating |
|---|---|---|---|
| Flexxbuy | High-ticket services, multi lender approvals | From $149 | ⭐ 3.5 |
| Affirm | Big-ticket online retail | Per-sale merchant fee | ⭐ 4.4 |
| Klarna | Pay in 4 for online shops | Per-sale merchant fee | ⭐ 4.3 |
| Afterpay | Fashion and beauty brands | Per-sale merchant fee | ⭐ 4.2 |
| PayPal Credit | Stores already on PayPal | Free for shoppers | ⭐ 4.0 |
| LendingClub | Patient financing and personal loans | Varies by loan | ⭐ 4.1 |
Quick picks:
- Best overall: Affirm — trusted brand with clear, fixed payment plans.
- Best budget option: PayPal Credit — no extra setup if you already take PayPal.
- Best for beginners: Afterpay — simple pay-in-4 that shoppers already know.
- Best for healthcare providers: LendingClub — strong patient financing programs.
🎯 Flexxbuy Alternatives
Looking for Flexxbuy alternatives? Here are the top options:
- 🌟 Affirm: A top pick for large online purchases. Shoppers see the total cost upfront with no hidden fees.
- 🚀 Klarna: Huge shopper base and fast pay-in-4 checkout. Great for high-volume e-commerce stores.
- 👶 Afterpay: Easy to set up and easy for shoppers. Best for small fashion and beauty purchases.
- 💰 PayPal Credit: No new account needed if you already use PayPal. Shoppers get a revolving credit line.
- 🏢 LendingClub: Strong for patient financing and personal loans. Good for clinics with larger bills.
⚔️ Flexxbuy Compared
Here’s how Flexxbuy stacks up against each competitor:
- Flexxbuy vs Affirm: Affirm wins for online retail. Flexxbuy wins for services and lower credit scores.
- Flexxbuy vs Klarna: Klarna is better for small carts. Flexxbuy handles loans up to $100,000.
- Flexxbuy vs Afterpay: Afterpay is pay-in-4 only. Flexxbuy offers long terms up to 84 months.
- Flexxbuy vs PayPal Credit: PayPal Credit is one lender. Flexxbuy shops your customer to 30+ lenders.
- Flexxbuy vs LendingClub: LendingClub is a single lender. Flexxbuy gives more approval chances across credit profiles.
My Experience with Flexxbuy
Here’s what I found when I dug into Flexxbuy.
The research: I looked at how a small service business would use it to offer financing on $2,000 to $10,000 jobs.
What I checked: Pricing, lender terms, the application flow, and 249 merchant reviews.
| What Flexxbuy Claims | What I Found |
|---|---|
| Higher approval rates | Backed by 30+ lenders and instant multi-lender decisions |
| Fast funding | Merchants report payouts within 24 to 72 hours |
| Easy to use | Applications take about a minute |
| Great support | 4.8/5 on Trustpilot, with support praised often |
What surprised me: The reviews are full of praise for Flexxbuy representatives by name.
One merchant called it a very smooth first transaction. Another thanked the team for much appreciated guidance.
A dog training academy owner said the team did an amazing job. Great service shows up again and again.
What frustrated me: Rates aren’t shown before your customer applies.
One reviewer also noted some lenders tightened approval rules.
Would I recommend it? Yes, for service businesses with big tickets. It turns “I can’t afford it” into “I can do that monthly.”
⚠️ Warning: Always tell customers to read their loan terms. A high interest offer can sour the relationship, even if the sale closes.
Final Thoughts
Get Flexxbuy if: You sell high-ticket services and lose deals over price.
Skip Flexxbuy if: You run a small online store with low-priced items.
My verdict: Flexxbuy isn’t flashy.
But it does one job well. It gets more customers approved.
For under $200 a year, that’s a cheap way to win back lost revenue.
Browse more customer financing tools if you want to compare.
Rating: 3.5/5
Frequently Asked Questions
How does Flexxbuy work?
You send customers one application link. Flexxbuy sends it to 30+ lenders. Customers compare offers, pick one, and get approved. Funds go to them or straight to your business.
What is flexible financing?
Flexible financing lets buyers pick their payment options. They choose the term and monthly amount that fits their budget, instead of paying the full price upfront.
What is retail financing?
Retail financing is a loan offered at the point of sale. A store partners with lenders so shoppers can buy now and pay over time.
How do I qualify for a flex loan?
Most lenders check your income, ID, and credit. A soft pull often comes first. A multi-lender platform like Flexxbuy improves your odds if your credit isn’t perfect.
Is a flex loan a good idea?
It can be, if the rate is fair and the payment fits your budget. Avoid high-interest offers for things you don’t truly need.


 English
 Spanish
 Chinese
 German
 French
 Arabic
 Russian
 Portuguese
 Japanese
 Korean
 Italian
 Turkish
 Dutch
 Polish
 Indonesian
 Thai
 Vietnamese